The new structure brings together our expertise in metals, chemicals, clean energy and circularity, with dedicated pages for consulting, continuing professional education, insights and company updates.
I’d welcome your feedback on the content, navigation and mobile experience as we continue testing and refining it.
NB. This article was first published on LinkedIn by Dr Michelle K. Lynch CChem FRSC as an edition of the Inconvenienced™ Newsletter
DISCLAIMER: This article draws on publicly available safety notices, technical literature and incident reports. Findings concern the specific products and formulations cited; reported incidents do not independently establish causation. References to companies or chemicals are not endorsements and the author has no commercial relationship or business involving any of the products mentioned. Nothing in this article is intended as commercial, financial, technical, safety, hazard or medical advice. Errors and omissions excepted.
The Squishy Spectrum
Counterfeit toys is a topic I came across around a year ago, although the context then was unsold goods. My concern began with what happens to toys that never reach a child: the resources used to manufacture them, the stock that accumulates and the eventual disposal. More recently, the question has become what happens to the toys that do reach children.
I have started seeing reports about children being injured by supposedly “fake squishies” bought online. The injuries deserve serious attention, and so does the language used to explain them. When “fake” becomes an umbrella term for unfamiliar or unbranded products, the story risks becoming Good Squishy, Bad Squishy: a familiar brand receives the benefit of the doubt while other manufacturers, including potentially competent producers of affordable generic goods, inherit the blame. There is room in that story for an equally convenient subplot: blaming consumers for making online purchases of “bad squishies” i.e., bad consumers.
I sense a little too much convenience creeping in, which of course I cannot allow to go unmentioned. Welcome to Inconvenienced™ — the newsletter that takes a solid approach to assessing supply chains gone awry, even the squishy ones.
The first question is what we mean by a brand. The American Marketing Association defines it through distinctive features that identify goods or services. That function does not require fame, a premium price or a large market share; it also leaves product safety and environmental performance to be established through other evidence. [1]
Counterfeit is more complicated because it requires us to identify what has been copied and which rights have been infringed. The WTO’s TRIPS Agreement distinguishes counterfeit trademark goods from pirated copyright goods, with definitions that refer to the relevant intellectual property and the law of the importing country. An unfamiliar manufacturer, a similar texture or a dumpling-shaped toy does not, by itself, establish either category. [2]
So rather than Good Squishy / Bad Squishy – perhaps we should think of them as on a spectrum. (See Table 1.)
Table 1. The Squishy Spectrum – definitions used in this article
Squishy describes the feel of a toy category that can include foam, rubber, silicone and products containing gel, beads or water. These different constructions already suggest that a single good-versus-bad narrative is asking a great deal of one adjective. Consumers need information about the particular product, its supplier and its contents to make an informed choice. [26]
I must confess at this point to having succumbed to buying a toy today – purely for research purposes – that falls within the spectrum of soft / sensory / squishy toys. Furthermore, I must admit to having enjoyed its novelty. I have no idea of its composition. I assume there must be sufficient elastomer in there as it will bounce a few feet off the ground. To my joy, I discovered that there is also a small battery cell inside it that activates a flashing light display when bounced. It’s a premium squishy, brand or no. It’s quality.
No doubt for safety reasons, the manufacturers have sealed the unit, so once I’ve exhausted the battery, it will lose its luminescent properties and I will be left with a squeezy, bouncy, spikey ball that doesn’t light up anymore. That’s unless I decide to intervene and make some design improvements – purely for sustainability purposes. Either way – it is a fun little stressbuster, and I can fully appreciate why these toys are popular.
There are documented concerns involving named businesses and branded products. Table 2 distinguishes formal recalls and safety findings from reports submitted to the US Consumer Product Safety Commission’s SaferProducts database. Those incident reports record what the submitter says happened; they do not independently establish the injury mechanism, authenticate the individual toy or amount to a recall.
Table 2. Companies, products and documented concerns
The Pinch Family doughnut is particularly instructive: an official report identifies serious chemical and choking risks while expressly recording that the product is not counterfeit. It demonstrates why authenticity and safety need their own evidence. The asbestos notices also retain an important qualification: the fillings may be contaminated, which should not be rewritten as confirmation that every affected toy contained asbestos. [17][10][11][12][13][14]
The CPSC’s August 2026 alert warns about fake and counterfeit squishies, while also advising consumers to stop using any squishy with an unknown manufacturer, missing safety information, leakage or other signs of concern. It separately warns that squishy toys can become dangerously hot in sunlight, hot vehicles or near heaters, and must never be microwaved. Those broader warnings deserve to travel with the counterfeit headlines because they concern product behaviour as well as product identity. [5]
Squishy Chemistry
Chemically, the category is more varied still. A slow-rise foam toy, a gel-filled cube and a sand-filled stretch animal can look equally squishy while presenting different exposure pathways.
Table 3 covers common material systems and chemicals documented in formulations or testing, including related slime and modelling-dough products. It is a guide to the questions a formulation raises, rather than a recipe for every toy or a claim that each listed substance is widespread.
Table 3. Chemicals and materials in squishy and related sensory toys
Benzene and asbestos belong in a different part of this discussion: the records above identify a chemical finding and suspected contamination in particular products, rather than establish either substance as a normal formulation ingredient. Similarly, an industrial raw-material safety data sheet tells us about that material’s assessed risks, hazards, handling, storage and transport conditions; the finished toy still needs assessment under realistic conditions of use. Its shell, contents, accessibility, emissions and foreseeable failure all matter. [15][14][25]
The patent trail for alternatives to boron-containing gellants is revealing. The 1994 modelling-dough patent US5364892A names sodium tetraborate as its preferred gelling agent. The later US7897659B2 discusses concerns about earlier borax-containing formulations and describes a system that omits the borax cross-linker, using maltose and maltitol to increase viscosity. These documents record deliberate changes in formulation chemistry; establishing which commercial toys use which system requires a connection to the actual product. [20][21]
Squishy Realities
The squish itself is an engineered property, and producing it can involve quite a collection of materials and additives. Take just one example: SEBS, styrene–ethylene/butylene–styrene, a polymer used in soft thermoplastic elastomer compounds. Its production starts with three different hydrocarbons, and is polymerised with catalysts. Compounders can then blend it with oils, other resins, fillers, inks, colourants and stabilisers, depending on the formulation. [28][29][30] That is before we get to any filling, decoration or packaging.
By expecting a squishy, or any other retail product for that matter, to be legally compliant, we are asking all the chemical producers, polymer manufacturers, compounders, additive suppliers and toy makers to employ integrity consistency across the supply chain.
So that means never failing on supply chain audits, appropriate ingredients, controlled processing, reliable testing and honest disclosure.
The fact is that brand or not, a toy combining many properties: i.e., soft, stretchy, bouncy, multi-coloured, and other visually pleasing, exciting and sensory features come with inherent risk multiplication.
I am perfectly willing to accept that these toys are novel, funny and enjoyable. The trade-off is that the darn thing brings a mini-chemical factory’s worth of supply-chain decisions into your hand. Maybe the realistic proposition is – you pay your money, and you take your choices.
That is where the Good Squishy, Bad Squishy story begins to lose its usefulness. A recognised brand can provide traceability, meaningful testing and a business that consumers can contact, all of which are valuable when things go wrong. Those advantages should support scrutiny of that business’s products. They should also leave room for an independent manufacturer to demonstrate good quality and safety through equally credible evidence.
Brand should not beget dominance
I want consumer protection to reward safe products and responsible stewardship, including affordable generic goods that meet the requirements. Turning brand familiarity into an informal admission ticket could favour market incumbents while making it harder for smaller producers to compete. The relevant evidence includes formulation, manufacturing controls, durability, exposure testing and clear information about what happens when the toy fails.
The supply-chain questions continue after the squeezing stops. What went into the shell and filling, how much unsold stock remains, and what happens to broken toys and their packaging? Who can explain the disposal route and substantiate environmental claims? Those questions belong with every manufacturer, because a safety assurance gives us only part of the information needed to assess lifecycle stewardship.
Parents deserve clear warnings and usable information about the products they are buying. Manufacturers, importers, retailers and regulators each have information and responsibilities that cannot be compressed into a judgement about a consumer’s shopping choices.
When a product is described as counterfeit, the report should explain the basis for describing it as counterfeit; when it is dangerous, it should explain the hazard and the action required.
Good Squishy can bring its logo to the interview, along with its test results, formulation evidence and disposal instructions. Bad Squishy should bring the same evidence. I am happy to hear both statements before deciding who gets to leave the station.
Since INEOS’s decision to idle its acetyls units at Saltend, Hull, Sir Jim Ratcliffe has made scathing public comments about UK economic policy and industrial strategy. In doing so he has left out part of the causation: INEOS’s own role in the global acetic acid business.
A second part of the Hull story has also been missed in this week’s coverage. That is the blow the idling represents to UK catalysis infrastructure, at a moment when national energy security and sovereignty need it more than ever.
Sir Jim is right about one important thing. British chemical production has a serious energy-cost problem. What does not follow is that UK government policy, by itself, explains why INEOS is mothballing Hull.
This article looks at how INEOS, like many other chemical licensors and producers, ended up competing against itself globally and came up short in its higher-cost regions. These were complex board-level decisions rather than poor ones. That is all the more reason to disentangle them.
What did INEOS actually announce?
On 22 September 2026, INEOS announced that all three of its acetyls production units at Saltend would be mothballed until further notice. It has not announced a permanent closure. Sir Jim Ratcliffe was quoted by The Guardian as saying: “I’m sure people will find it hard to believe that we are being forced to mothball some of the most efficient plants in Europe … we just cannot compete.” The same article quoted him describing the UK government’s energy policy as “leading to economic vandalism on an industrial scale”.
Trade press coverage adds the scale: 500,000 t/y of acetic acid and 350,000 t/y of acetic anhydride and ethyl acetate; 245 INEOS staff directly affected, with up to 755 more across the site’s supply chain.
The UK gas price situation
Reuters reported UK front-month gas at around $23.51/MMBtu against $2.84/MMBtu at Henry Hub in the United States: a contemporaneous differential of about 8.3 times. Ratcliffe used INEOS’s own comparison of 12 times the US level and eight times the Chinese level, the Chinese figure referring to coal-based production. Whichever comparison is used, the underlying energy disadvantage is substantial, even though the precise ratio depends on the energy source, the contract and the plant configuration.
The longer history of UK industrial energy pricing puts September’s number in context. The Office for National Statistics found that UK industrial electricity prices in 2023 were 46 per cent above the median of reporting IEA countries and roughly four times those in the US and Canada. Industrial gas prices followed a different pattern, sitting 7 per cent below the IEA median in the same year. The ONS attributes the escalation in wholesale gas costs since 2021 first to international supply-chain pressure as the world economy recovered from the pandemic, then to Russia’s invasion of Ukraine, with the UK and the rest of Europe increasingly reliant on more expensive imported LNG.
Figure 1. UK non-domestic gas and electricity prices for very large consumers, 2004 Q1 to 2026 Q1 (DESNZ Quarterly Energy Prices, Table 3.4.1, excluding CCL), and the spot gas differential of 22 September 2026 (Reuters).
The latest price shock has been amplified by disruption arising from conflict in the Middle East. Energy policy therefore forms part of Hull’s operating environment alongside an international gas market whose movements are not determined in Westminster.
INEOS’s global acetic acid business: from the 2020 BP deal to today
The wider question begins with the structure of INEOS Acetyls itself. Hull is one production location inside a multinational production, technology and commercial system. INEOS bought that system from BP for $5 billion, roughly £4.05 billion at the exchange rate when the deal was agreed in June 2020, and completed the purchase on 1 January 2021.
The transaction covered 15 sites and 10 major joint ventures across aromatics and acetyls, so it would be misleading to allocate the whole purchase price to acetic acid. It did, nonetheless, transfer to INEOS a global acetyls platform: the Hull operations, the Asian joint ventures, the technology and intellectual property, the commercial relationships, and interests spanning several major production centres. Sir Jim Ratcliffe described the acquisition at the time as “extending our position in global petrochemicals and providing good scope for expansion and integration with our existing business”.
That acquisition matters to the present argument because ownership changed the nature of the competitive problem. INEOS did not subsequently face American and Asian acetic acid production solely as an outside market force. It owned, part-owned, supplied technology to, supported or commercially participated in important parts of that production system.
INEOS Quattro’s 2024 annual report describes the five Asian acetyls joint ventures as partnerships with “leading producers in the region benefiting from site integration and advantageous feedstock supply”. INEOS holds board appointment rights at each venture, is responsible for their technology and catalyst support, is their sole supplier of catalyst, and holds exclusive off-take rights for all of their exports. According to S&P Global, cited in the same report, INEOS is the world’s second-largest acetic acid producer with about 14 per cent of global capacity. Asia is its largest region by sales volume and capacity, North America is second, and Europe is the smallest.
The same report records the capital trail. In 2020 and 2021, spanning the handover from BP, the business invested in a debottlenecking project and a new VAM plant at its Ulsan joint venture in South Korea. In 2024 it converted Ulsan’s feedstock from low-sulphur fuel oil to natural gas, a project INEOS expects to improve the joint venture’s economic position and add capacity. At Chongqing it invested in a 70,000 t/y debottleneck commissioned in 2022.
Hull did receive significant investment. In July 2025 INEOS completed a £30 million project converting part of the site’s energy supply from natural gas to hydrogen produced as a co-product of existing processes, which the company says cut the site’s carbon emissions by 75 per cent. Management was prepared to spend money at Saltend; the site was not left technologically frozen after the BP acquisition. But the capital deployed elsewhere served a different purpose: it expanded, secured or improved production in lower-cost regions.
Texas City is the clearest example. Before INEOS owned the site, Eastman operated its 600,000 t/y acetic acid plant there under an INEOS Cativa® licence, and INEOS marketed the output. The 2024 annual report states that the Acetyls business received 63 per cent of the profits from that arrangement. INEOS therefore already had direct economic exposure to US acetic acid production while Hull remained its European base.
In December 2023 INEOS converted that relationship into ownership, buying the Texas City site from Eastman for $490 million, about £386 million at the completion-date exchange rate. The transaction included the 600,000 t/y acetic acid unit and the site’s third-party activities. INEOS described the asset as “strategically important” and “in a cost advantaged location”, and its acquisition announcement emphasised access to competitively priced feedstocks. The logic was straightforward: ownership gave INEOS full participation in a large US Gulf Coast producer whose energy and feedstock position was structurally better than anything available to Hull.
The direction of travel had been visible before the purchase. In June 2022 INEOS launched a feasibility study for a new world-scale acetic acid and derivatives complex on the US Gulf Coast, identifying “the abundance of competitively priced feedstocks” as the region’s advantage. In the same announcement it said it would not proceed “at present” with a previously announced VAM plant in the UK “given the volatile and uncompetitive energy costs outlook”. The Texas City acquisition later gave the business an established route to the position it had been exploring through a greenfield project.
By 2024 the relationship between US production and European competitiveness was being described explicitly inside INEOS. In INEOS in Review 2024 (pages 7–8), David Brooks, chief executive of INEOS Acetyls, said the business had found it “very difficult to remain competitive during the past two-to-three years because of high natural gas prices in Europe, as well as cheaper imports into the region”, and had responded by “optimising its assets, essentially bringing in lower-cost tonnes from the US, when necessary”. The Texas City acquisition, he added, “has enabled us to optimise US production to supply customers anywhere in the world with the lowest-cost tonnes in our system”.
Those statements matter for what happened at Hull this week, because they describe the mechanism by which global “portfolio optimisation” is not optimal for each individual plant. A producer seeking the lowest-cost tonne directs production, logistics and customers towards the assets that provide it. Hull competes inside INEOS’s optimised portfolio as well as against the lowest-cost plants owned by Celanese, Eastman, Chinese producers and other external suppliers.
INEOS’s acetic acid focus remains global
China
China introduces another force independent of the UK policy question. In the same 2024 review, Brooks said Asia “is in a world of pain” because of Chinese overbuilding, including in acetic acid, and that “a huge amount of new acetic acid capacity is due to go onstream in China later in 2025 and into early 2026, which will obviously depress prices and margins worldwide”. His outlook was blunt: “No one is looking at acetic acid over the next few years with any enthusiasm.” Hull entered the current energy shock already operating in a market facing weak demand, growing supply and unprecedented pressure from Chinese imports.
Figure 2. Share of world acetic acid nameplate capacity by region, 2000 and 2025 (EnabledFuture acetic acid register; 2000 approximate).
Table 1. Acetic acid nameplate capacity by world region, 2000 and 2025
Region
2000 capacity (Mt/y)
2000 share
2025 capacity (Mt/y)
2025 share
Change in share
China
0.7
10%
13.9
60%
+50 points
North America
2.8
39%
4.2
18%
−21 points
Asia excl. China
2.0
28%
3.5
15%
−13 points
Europe incl. Russia & CIS
1.6
22%
0.75
3%
−19 points
Middle East
0
0%
0.6
3%
+3 points
Other
0.1
1%
0.1
<1%
−1 point
World
7.2
100%
23.1
100%
Nameplate capacity of established plants. 2025 from the EnabledFuture acetic acid register at end-2025, with Hull counted as operating; Europe falls to about 1 per cent once Hull is idled. 2000 is an EnabledFuture reconstruction from producer records and is approximate (±20 per cent); the Chemical Economics Handbook put 2003–05 virgin production at about 5 Mt/y, roughly half in the US, 1 Mt/y in Europe and 0.7 Mt/y in Japan.
India
Despite Chinese cost pressure that had been building since the start of the decade, INEOS nurtured an existing relationship with another partner for mega-scale acetyls capacity. In November 2024 it signed a memorandum of understanding with India’s Gujarat Narmada Valley Fertilizers & Chemicals (GNFC) to explore a new 600,000 t/y acetic acid plant at Bharuch. INEOS identified India as a key growth market; GNFC noted that the country imports around 85 per cent of its acetic acid. That makes sense for a national ecosystem. What it does not speak to is the redundancy it creates elsewhere, nor the reaction such a decision provokes from China’s domestic producers, who are well known to cultivate market conditions, including sharp price discounting, that make life hard for new capacity. The two sides then fight it out with anti-dumping measures and, worse, trade wars. Smaller, higher-cost plants like those in the UK are inevitably the worst affected.
The USA
INEOS is an honoured guest in the USA, and its Texas City complex continues to receive strategic support. In April 2026 INEOS announced that it would become a shareholder and anchor customer of Sandpiper Chemicals’ proposed low-carbon methanol plant at the site. According to Gas World, the project is designed for about 1.1 million t/y of methanol from natural gas with carbon capture, at a total investment of around $1.7 billion, roughly £1.25 billion at the announcement-date exchange rate. Up to 300,000 t/y of that methanol is intended for INEOS’s acetic acid production at Texas City. The project places additional feedstock infrastructure around an already cost-advantaged US asset and extends its operating horizon into the next decade.
The acetic acid technology legacy
Technology deserves a mention, given its effect on production economics and global competitiveness.
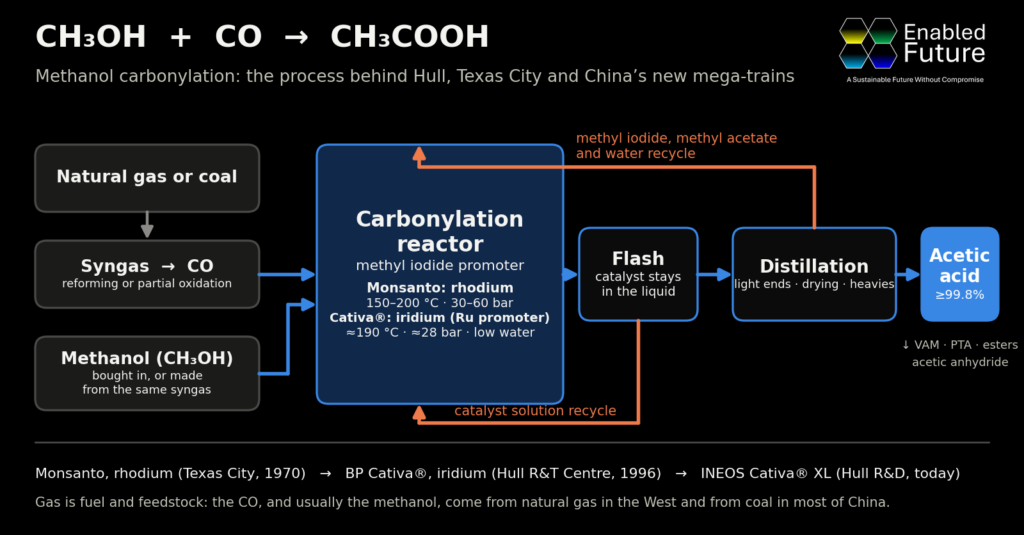
Acetic acid is made by the catalytic carbonylation of methanol. Most large plants are back-integrated to a fossil feedstock: mainly natural gas in Western plants, and natural gas or coal in Asia, with a few facilities relying on naphtha.
Figure 3. Methanol catalytic carbonylation to acetic acid: feedstocks, reactor, separation train and recycles, with the catalyst lineage from Monsanto’s rhodium process to BP’s Cativa® and INEOS’s Cativa® XL.
The technology’s intellectual history long predates INEOS. Monsanto commercialised the original methanol carbonylation process in 1970 and BP acquired it in 1986. As Jane Jones documented in Platinum Metals Review in 2000, writing from BP Chemicals’ Hull Research & Technology Centre, BP’s Cativa process replaced Monsanto’s rhodium catalyst with an iridium catalyst promoted by ruthenium, allowing less severe process conditions and commercially viable large single-train units. Cativa went on to underpin BP’s, and now INEOS’s, plants in the US, the UK and Asia, as BP expanded the acetyls business from Hull through joint ventures and licences.
BP’s decision to sell its acetyls and aromatics businesses to INEOS came in 2020. Since then INEOS has continued to operate, optimise and commercialise the technology. Its 2024 annual report states that Cativa “has been continuously optimized and commercially operated in multiple plants since first being deployed over 25 years ago”, and that the latest version, Cativa XL, “offers advantaged capital efficiency through reduced process complexity and variable cost improvements through efficient heat integration leading to reduced steam consumption”.
The register behind this article shows something else about technology, and it sits entirely outside the gas price. China’s new capacity is not being built on Western licences. Jiangsu Sopo and Yankuang run on process technology from the Southwest Research & Design Institute of Chemical Industry. The Huayi group runs its own carbonylation package at Anhui and Guangxi, and when it shut the Wujing plant in September 2025, the first plant BP licensed in China, in 1993, it replaced the tonnes with a new 800,000 t/y unit of its own at Caojing. Juzhengyuan’s 1.5 million t/y train at Jieyang, the largest in the world, runs on what its owner describes as domestically developed rhodium technology. Kingboard’s 800,000 t/y plant at Xingtai goes a step further, using carbon dioxide captured from its own flue gas, with low-energy capture technology developed at Tsinghua University, as part of its feedstock. A BP licence has been retired, and China’s research institutes and universities now supply the process, catalyst and carbon technology for most of the capacity being added anywhere in the world. That is a competitive fact about research capability, not about Westminster, and it puts a premium on INEOS’s ability to keep Cativa ahead. INEOS’s own annual report says that work is done in Hull.
An unwitting casualty of the Hull mothballing: UK catalysis
There is one fact that the entire gas-price and policy squabble misses. Hull was an early UK hero of catalysis. The science behind Cativa originated largely with BP scientists at Saltend and with Johnson Matthey at Royston, Hertfordshire, and it gave a British site the process that the rest of the world’s producers had to match. Hull remains INEOS Acetyls’ global R&D site: the 2024 annual report records 20 full-time R&D staff there, focused on improving operating costs and supporting the joint ventures. The question that should sit alongside the gas price is whether the UK government and UK industry ever did enough to support that capability, and whether they are doing enough now. It should arguably be the basis for a rethink of government support for the Hull sites, which still house world-class scientists and scale-up facilities alongside the production plants.
The UK excels at catalysis and chemical process technology. It ships the hard-earned results around the globe, and catalyst and catalytic-process products and services have contributed billions to the UK trade balance over the last half-century. One might ask whether that initial return on investment is now eating itself. The answer might be: only if we keep placing the emphasis on domestic production, when our real skill and opportunity lie in research and innovation.
If, on the other hand, the emphasis is domestic capacity competitiveness, that ought to have been factored into the engineering, licensing and production contracts and their pricing. Arbitrage was always going to be the enemy. Licensing contracts could have been structured so that low-cost production headed for export markets carried higher royalties, set high enough to stem the ability of any single country or company to dominate.
The problem with that approach is that only one producer or licensor needs to prioritise short-term gains, and most Western chemical producers and licensors have. They built castles in low-cost regions, migrated their customer base along with them, and then completed the transaction by moving their operations out of the UK and Europe altogether. Compared with that full relocation, INEOS has shown considerably more loyalty to the UK than most, and a real commitment to low-carbon feedstocks and energy-efficient projects. But it still played a strong role in globalisation, and not only in acetic acid; olefins are a case in point. EnabledFuture maintains its position: you cannot expect to compete against yourself. One of you is going to lose.
Where criticism of the UK government does stand up to scrutiny is the decision to drop support for one of our most prized technology sectors: catalysis. EnabledFuture would like to hear leading business figures such as Sir Jim Ratcliffe amplifying that point, in their technology-package pricing as well as in their public commentary. He could start with the Acetyls R&D team in Hull, and add the decision by Westminster to make over £160 million of science research budget cuts, including those affecting the Science and Technology Facilities Council’s Oxfordshire facilities at Harwell. The Diamond synchrotron and STFC’s ISIS neutron and muon source there are where UK researchers watch catalysts working under real process conditions, and the UK Catalysis Hub itself is based on the same campus. For catalytic science, that infrastructure is indispensable.
Whose accountability is it anyway?
Accountability is not quite the right question; the better one is what should be accounted for. Answering it well means drawing a wider causal boundary than the one implied by a comparison between the UK gas price and Henry Hub.
The current energy differential is damaging and, at September 2026 prices, Hull faces an exceptionally difficult operating environment. That much is settled. As this article has laid out, INEOS, like many of its peers, has also invested considerably in global activities that do not support the continued operation of its UK and EU assets.
That determines what policymakers should establish before considering support for the site. The supply-chain question is where the tonnes previously made at Saltend will now come from, and how much of the replacement volume will be supplied from INEOS-controlled or INEOS-supported capacity in the United States and Asia. The commercial question is what level of energy-cost relief would change the preferred production location inside INEOS’s own network, and what capital and operating commitments INEOS would make at Hull if that relief were provided. The downstream question concerns the roughly 90 European acetic acid customers identified in INEOS’s reporting, including the two co-located at Saltend, INEOS Europe and Mitsubishi, whose own cost and supply positions change when UK and EU capacity disappears.
The government’s initial response, £350 million of co-investment for strategically important chemicals producers and electricity-cost relief through the Supercharger and British Industrial Competitiveness schemes, addresses electricity, not the gas exposure at the centre of INEOS’s argument.
This is where the attribution of responsibility becomes clearer. The evidence supports Sir Jim Ratcliffe’s warning that the UK and European energy environment can destroy the economics of energy-intensive chemical production. It also establishes that INEOS, along with many other Western chemical supply-chain players, has been an active architect of the global production system against which Hull competes. These causes operate together.
Public policy sets part of the regional cost base; global capacity investment determines supply; technology licensing spreads production capability; corporate capital allocation strengthens selected assets; procurement and feedstock choices determine variable cost; and portfolio optimisation decides which tonnes reach customers. For Hull, all of those decisions have now converged.
A complete account of the mothballing therefore has to include the price of British energy and carbon alongside the capital INEOS has put into the USA, China and India, and the licensees, new and inherited, that it continues to support. Leaving those factors outside the causal boundary would transfer accountability away from decisions that materially changed the competitive landscape. It would also risk ignoring the real skills and opportunities that sit inside the Saltend site.
For governments and downstream supply chains, the issue is therefore larger than whether one company should receive lower energy costs, or whether business customers should be supported more than households, or whether the real matter is not price at all but security of supply. In which case INEOS is the most heard case study, but not the most vital. Those are matters for energy producers and policymakers to deliberate. What EnabledFuture would like to see is recognition that without the catalyst science, the whole topic would be moot, because the UK would not be participating in the front-end development of new, more efficient chemical processes as it was three decades ago, when Cativa emerged as the most prestigious acetic acid technology on the planet.
Unless we shore up our commitment to nurturing the UK’s world-class contribution to industrial catalysis, we risk seeing that disappear to foreign shores too, to places where governments are prepared to give it the attention and capital it deserves. That would be a national disgrace, with a future price tag none of us is prepared for.
EnabledFuture Global Technology Competitiveness Dashboards
The content in this article was generated from the EnabledFuture Global Technology Competitiveness Dashboard for acetyls. Offered as a subscription service, it covers plant ownership and equity participation, nameplate capacity, operating status, feedstocks, plant configuration, technology lineage, licensing relationships, catalysts, precious-metal consumption and downstream supply chains. Please enquire for a demonstration.
Research cut-off: 24 September 2026. Monetary conversions are approximate nominal sterling equivalents at contemporaneous exchange rates. Project investment is not attributed to INEOS where its equity contribution has not been publicly disclosed. Plant and technology evidence prioritises company filings, official disclosures and primary sources.
References
1. INEOS. INEOS idles Europe’s last world-scale Acetyls plant as energy prices hit 12 times US level. 22 September 2026. https://www.ineos.com/news/shared-news/ineos-idles-europes-last-world-scale-acetyls-plant-as-energy-prices-hit-12-times-us-level/
2. The Guardian. Jim Ratcliffe halts production at Hull chemical plants as gas prices soar. 22 September 2026. https://www.theguardian.com/business/2026/sep/22/jim-ratcliffe-halts-production-hull-chemical-plants-gas-prices-ineos-uk
3. The Chemical Engineer. Humberside engineers “distressed” as INEOS suspends UK acetyl production over high gas prices. September 2026. https://www.thechemicalengineer.com/news/humberside-engineers-distressed-as-ineos-suspends-uk-acetyl-production-over-high-gas-prices/
4. Reuters. INEOS to mothball three chemical plants as high energy costs hit production. 22 September 2026. https://www.reuters.com/world/uk/ineos-mothball-three-chemical-plants-high-energy-costs-hit-production-2026-09-22/
5. Office for National Statistics. The impact of higher energy costs on UK businesses: 2021 to 2024. https://www.ons.gov.uk/economy/economicoutputandproductivity/output/articles/theimpactofhigherenergycostsonukbusinesses/2021to2024
6. Department for Energy Security and Net Zero. Quarterly Energy Prices, Table 3.4.1: Prices of fuels purchased by non-domestic consumers in the UK. Published 30 June 2026 (2026 Q1 provisional). https://www.gov.uk/government/statistical-data-sets/gas-and-electricity-prices-in-the-non-domestic-sector
7. INEOS. INEOS completes the acquisition of BP’s global Aromatics & Acetyls business. 1 January 2021. https://www.ineos.com/news/shared-news/ineos-completes-the-acquisition-of-bps-global-aromatics–acetyls-business/
8. BP. bp agrees to sell its petrochemicals business to INEOS. 29 June 2020. https://www.bp.com/press-and-publications/press-releases/bp-agrees-to-sell-its-petrochemicals-business-to-ineos
9. INEOS Quattro Holdings Limited. Annual Report 2024, The Acetyls Business, pp. 91–98. https://www.ineos.com/globalassets/investor-quattro-ir/public/annual-reports/ineos-quattro-holdings-limited—annual-report-2024.pdf
10. INEOS. INEOS invests £30 million to slash emissions at Hull site by 75%. 17 July 2025. https://www.ineos.com/news/shared-news/ineos-invests-30-million-to-slash-emissions-at-hull-site-by-752/
11. INEOS. INEOS completes the acquisition of the Eastman Texas City site. December 2023. https://www.ineos.com/news/ineos-group/ineos-completes-the-acquisition-of-the-eastman-texas-city-site/
12. INEOS. INEOS to build world scale acetic acid plant and associated derivatives on US Gulf Coast. 16 June 2022. https://www.ineos.com/news/shared-news/ineos-to-build-world-scale-acetic-acid-plant-and-associated-derivatives-on-us-gulf-coast/
13. INEOS. INEOS in Review 2024, pp. 7–8 (INEOS Acetyls). https://www.ineos.com/contentassets/f05d7065b5b84a9ba261effcab530850/ineos_in_review_2024.pdf
14. INEOS. INEOS and GNFC sign a Memorandum of Understanding to build a new world scale acetic acid unit in India. 20 November 2024. https://www.ineos.com/news/shared-news/ineos-and-gnfc-sign-a-memorandum-of-understanding-to-build-a-new-world-scale-acetic-acid-unit-in-india/
15. Gas World. INEOS and Sandpiper to develop $1.7bn blue methanol plant in Texas City. April 2026. https://www.gasworld.com/story/ineos-and-sandpiper-to-develop-1-7bn-blue-methanol-plant-in-texas-city/2248649.article/
16. Yoneda, N., Kusano, S., Yasui, M., Pujado, P. and Wilcher, S. Recent advances in processes and catalysts for the production of acetic acid. Applied Catalysis A: General, 221 (2001), 253–265. https://www.sciencedirect.com/science/article/abs/pii/S0920586100002637
17. Jones, J. H. The Cativa™ Process for the Manufacture of Acetic Acid. Platinum Metals Review, 44(3) (2000), 94–105. https://technology.matthey.com/article/44/3/94-105/
18. United States Court of Appeals for the Eighth Circuit. BP Chemicals Ltd v. Jiangsu SOPO Corporation, opinion of August 2005 (records BP’s 1993 licence to Shanghai-Wujing). https://ecf.ca8.uscourts.gov/opndir/05/08/041814P.pdf
19. Shanghai Huayi Energy Chemical Co. Ltd. Announcement on the permanent shutdown of the Wujing methanol and acetic acid units. Shanghai Securities News, 13 September 2025. https://paper.cnstock.com/html/2025-09/13/content_2120784.htm
20. China Chemical Industry News. Acetic acid production technology in China (Southwest Research & Design Institute of Chemical Industry technology at Jiangsu Sopo and Yankuang). 15 November 2005. https://www.chemnews.com.cn/c/2005-11-15/541364.shtml
21. PROCESS China. Juzhengyuan Jieyang 1.5 million t/y acetic acid unit enters trial production. January 2026. https://chem.jgvogel.cn/c1575033.shtml
22. Kingboard Holdings Limited. Announcement: acetic acid project in Xingtai, Hebei (800,000 t/y; Tsinghua University low-energy carbon capture technology). HKEX, 16 March 2026. https://www.hkexnews.hk/listedco/listconews/sehk/2026/0316/2026031600343.pdf
23. BBC News. Report on UK science research budget cuts affecting STFC facilities. 2026. https://www.bbc.co.uk/news/articles/cr4v0n3z16ko
24. UK Research and Innovation / Science and Technology Facilities Council. Rutherford Appleton Laboratory. https://www.ukri.org/who-we-are/stfc/facilities/rutherford-appleton-laboratory/
25. Malveda, M. P. and Funada, C. Acetic Acid. Chemical Economics Handbook, SRI Consulting, 2003 (2003–05 production estimates used as a cross-check for the 2000 regional figures).
26. EnabledFuture. Global Technology Competitiveness Dashboard for acetyls: acetic acid plant register. Research cut-off 24 September 2026 (source of Table 1 and Figure 2).
EnabledFuture (HQ London UK) does not support deep-sea mining of virgin metals or minerals.
We believe that the protection of marine ecosystems and biodiversity must take precedence over the extraction of new resources from fragile and poorly understood environments.
Damage to living species and ecosystems cannot be accepted as collateral damage in the pursuit of commercial objectives.
Our work on metals, minerals and industrial technologies is guided by the principles of the waste hierarchy / 9R framework, the United Nation’s Sustainable Development Goals (UNSDGs) and insights gained through research we carry out in our Hexazity®️ Tech Lab.
We prioritise solutions that minimise overall resource consumption, extend product lifetimes, support closed-loop material systems and reduce dependence on virgin raw materials.
Much of our research focuses on technologies that deliver significant reductions in metal demand while maintaining or improving performance, efficiency and reliability.
Where non-metal alternatives demonstrate a superior lifecycle environmental footprint, we include and evaluate those options objectively within our studies.
Increasingly, combinations of metal and non-metal systems are proving to be practical pathways towards reducing demand for newly mined materials while delivering effective technical performance.
EnabledFuture is critical of business models that assume endless growth in material consumption or that pursue market dominance through the rapid scaling of production capacity to multi-million-tonne levels without fully considering resource constraints and environmental impacts.
We are especially concerned that those strategies are leading to supply deficits in critical industrial metals and subsequently presenting deep-sea mining as a necessary commercial response.
The transition to a sustainable future must not become a race to extract more resources from increasingly vulnerable ecosystems.
Innovation should focus on resource efficiency, circularity, durability and responsible consumption rather than the continual expansion of material throughput.
EnabledFuture supports a future in which technological progress, industrial efficiency and environmental stewardship advance together.
EnabledFuture stands for A Sustainable Future Without Compromise.
EnabledFuture Announces New Mission: Supply Chain Appraisals for a Sustainable Future
3 December 2025
EnabledFuture, (London, HQ) founded in 2016 to drive sustainable technology portfolios across chemicals, catalysis, critical metals, hydrogen and battery value chains, has announced a major strategic shift. From December 2025, the company’s new mission looks to evaluate progress in supply chain adoption. This is reflected in the new strapline: “Supply Chain Appraisals for a Sustainable Future.”
The updated company mission reflects a move from sustainability planning to the role of an activist consultant evaluating whether industry is actually delivering on it promises. After a decade supporting the development of low-carbon and circularity toolkits, EnabledFuture has concluded that the pace of real deployment at scale lags far behind the promises made by many organisations. Furthermore, companies have operated against their own green ambitions by building up fossil-dependent activities in low-cost regions.
Dr M K Lynch, CEO of EnabledFuture, said: “We have championed technologies that could decarbonise industry. Yet commercial activities across many supply chains remain overwhelmingly tied to fossil-based growth. Our new remit is simple: to appraise progress honestly and to hold technology-driven sectors to the standards they claim to pursue. Our role at EnabledFuture is to ensure that sustainability is measured by what is built and operated at scale—not by promises.”
EnabledFuture will now focus on independent appraisals of supply chain activities, examining whether the services, products and investments being delivered match stated environmental goals. This includes assessing environmental impacts, clarifying where gaps exist between ambition and action, and identifying credible pathways toward more sustainable operations.
It will look for opportunities for renewed emphasis on the Circular Economy, the 10 R’s of the Waste Hierarchy and assessing progress against key frameworks such as the United Nations 17 Sustainable Development Goals (SDGs). Scrutiny of climate and ESG ratings will also be a central aspect of the new remit – including questioning how businesses with coal and other fossil based interests can receive “A” ratings, simply on the basis of pilot and future-based goals.
Through stakeholder engagement, and supply chain communication – EnabledFuture will play a facilitating role in understanding the roadblocks to achieving faster implementation of sustainable developments and to draw the supply chain’s focus back to the urgency of not only carbon reductions but also the amount of ecological damage their activities continue to cause in terms of harm to land, water, aquatic, mammal and human life.
Furthermore, the overproduction of goods that are never sold, yet count as “consumption” in market data must be addressed as this inflates the true need for new chemical plant capacity and associated infrastructure. Combined with the continued and unnecessary reliance on single-use items, bottled drinks and packaging – EnabledFuture believes that as much as 40% of plastic goods manufactured today could be made redundant.
Multi-million tonne chemical plants – built in low-cost regions with Western suppliers cooperation has imbalanced the geographic supply of basic chemical feedstocks almost to the point of criticality, while simultaneously making it economically unfavourable to open smaller, greener plants in their home territories. In EnabledFuture’s opinion, these companies are decentering the emphasis on green growth in their domestic Western locations – and dialing back on the green commitments which saw them win millions in government grant support.
Against this backdrop, EnabledFuture sees positive opportunities for disruption including from the growing global repair community which has already shown its ability to contribute to sustainability. This is something the company wants to see governments and policymakers prioritising over innovations that simply replace one single-use item material with another or do nothing to improve the longevity or repairability of consumer goods.
Dr Lynch added: “This evolution in our remit brings us home to our founding vision, with a sharper focus on overall impact reduction – circularity and an end to the business-as-usual unlimited supply of products with polluting lifecycles – defended with a sticking plaster of lower carbon intensity.”
At EnabledFuture, protecting client data and digital communications is as important as the sustainability strategies we deliver. Our recent independent security checks through the UK Government’s National Cyber Security Centre (NCSC) – “Check Your Cyber Security” service confirmed that our domain and email systems are well protected against spoofing, interception, and downgrade attacks.
Verified by the NCSC
Using the free government service, enabledfuture.com achieved clean results across all core security categories:
Category
Result
What it means
DMARC
✅ Strong policy (p=reject)
Fake emails pretending to come from EnabledFuture are automatically blocked.
SPF
✅ Passed all tests
Our authorised mail servers are clearly defined and validated.
TLS
✅ Up to date and valid
All email traffic is encrypted using modern standards (TLS 1.2 +).
MTA-STS
✅ Strong configuration
Emails to EnabledFuture are protected from downgrade attacks and forced to use encryption.
The service reported “No issues found” for anti-spoofing and email-privacy checks, confirming that EnabledFuture’s digital estate meets best-practice standards for authenticity and secure transmission.
Why this matters
Phishing and spoofing remain leading causes of data breaches worldwide. A strict DMARC policy, secure TLS configuration, and a verified MTA-STS policy ensure that communications with EnabledFuture cannot be impersonated or downgraded in transit. This reinforces the trust our partners and clients place in our digital channels.
Built on a foundation of best practice
EnabledFuture’s systems follow recognised best practice for data security and business continuity. All devices and accounts use two-factor authentication (2FA), enterprise-grade anti-virus protection, and routine software updates to ensure the latest security patches are applied. Regular reviews of access permissions, encrypted backups, and secure password management are standard parts of our operating procedures.
Our CEO, Dr MK Lynch, CChem, FRSC sums up these checks and improvements:
“EnabledFuture is proud to have taken a robust and proactive stance to cybersecurity and cyber-resilience – ahead of its competitors, and with a strong commitment to providing continued and trustworthy services to its expanding client base.”
Bridging the Knowledge Gap: Why Cross-Sector Training is Critical in the Era of Sustainable Industry
In a world racing toward decarbonisation, resource security, and circularity, one of the greatest risks to progress isn’t a lack of technology—it’s a lack of understanding.
Poor knowledge across value chains results in flawed decisions, missed opportunities, and costly misunderstandings between departments, partners, and regulators. Whether in chemicals, catalysts, batteries, hydrocarbons, or hydrogen, professionals are increasingly expected to make sense of complex industrial systems that extend well beyond their original expertise.
Yet too often, teams are forced to act without clarity:
Business developers pitch solutions they don’t fully grasp.
Policy teams struggle to assess technological feasibility.
Procurement and finance functions undervalue critical IP or process choices.
Sustainability strategies misfire due to unrealistic or siloed assumptions.
This isn’t a failure of talent. It’s a gap in foundational, cross-sector knowledge.
The Solution: Precision Training for a Converging World
At EnabledFuture, we’ve designed our training to close these gaps—quickly, intelligently, and without overwhelming busy professionals.
Each course we offer is built to demystify the complex: from catalytic processes and petrochemical markets to battery chemistry and hydrogen pathways. Participants walk away not only with better understanding but with the confidence to engage meaningfully across disciplines and across supply chains.
Whether you’re in strategy, sustainability, R&D, operations, or investment, our training will enable you to:
Make smarter decisions grounded in commercial and technical reality
Spot risk and opportunity where others see noise
Speak the language of process engineers, chemists, traders, and policymakers alike
Strengthen your credibility across internal and external stakeholder groups
Shape more robust, future-fit business strategies
Why It Matters Now
As industries restructure around net-zero goals, regulatory pressures, and shifting geopolitical landscapes, the cost of getting it wrong is rising. Training isn’t just professional development—it’s operational risk reduction.
EnabledFuture’s courses are modular, accessible online, and designed to sharpen your understanding in hours, not months. They’re also fully aligned with our Hexagon MBA structure, enabling professionals to build deep, cross-sector expertise over time.
The bottom line? Poor knowledge is expensive. Clarity is powerful. And in a world of accelerating change, the smartest teams are the ones that learn fastest.
We are delighted to have made a financial donation to UN Women which will go towards:
🚑 Providing life-saving assistance during crises, ensuring women and girls have access to shelter, food, and safety. 💜 Advocating for equal rights and opportunities, creating fairer societies where every woman’s voice is heard. 👯♀️ Empowering women and girls to break barriers, unlock their potential, and build a brighter, more equitable future.
We are also proud to have made the following official pledge for gender equality:
“EnabledFuture pledges to continue to campaign for fair representation of women in STEM jobs and to see a 50% figure reached for female speakers and panellists at scientific conferences and events.”
We very much look forward to the official UN Women’s wonderful festival of events and initiatives in 2025 as the world celebrates 30 years of achievement on the Beijing Declaration and Platform for Action, a visionary 1995 plan agreed by 189 governments to achieve the equal rights of all women and girls.
We hope that other organisations will support the official UN Women theme and that donations make their way to those that need them the most.
To all our colleagues, clients and supporters, we wish you a very happy International Women’s Day 2025!
Is Your Technology Portfolio Ready for a Sustainable Future?
Ensuring precious R&D funds are never wasted – technology directors know they must work towards profitable and sustainable technology portfolios. They also know they must mitigate economic and technical risks on scale-up – so they don’t create future headaches for the production side of the business. These folk are no strangers to the challenges of making the right choices in rapidly changing industries!
Are you asking yourself:
How can we prioritise our resources for the best sustainable technologies?
Can we ensure a stable supply of critical metals for our production?
What innovations in materials and recycling will keep us ahead of the competition?
At EnabledFuture, we understand these challenges—and we’re here to help you tackle them head-on.
What EnabledFuture Can Do for Your Manufacturing Business:
We specialize in helping technology leaders like you optimize your operations and stay ahead in the race for innovation. Here’s how we support your goals:
Expert Knowledge of supply chains and key developments in the catalysis, battery materials, hydrogen, and critical metals sectors, ensuring we can help you avoid costly mistakes and pitfalls.
Bespoke Reports that deliver detailed insights on the innovations and outlook for catalysts and batteries. Tackling areas where information can be tricky to find with our expert searching techniques and vast network of industry contacts.
Training Programs we provide structured and detailed training courses to empower your team with the latest advancements in carbon-efficient petrochemicals, renewables, catalysts, batteries and recycling technologies.
Industry Tracking essential analysis for up-to-date intelligence on battery materials, battery, fuel cell and solar PV recycling. Have these handy trackers at your fingertips, and you’ll never miss the opportunity to develop a new lead when it comes along!
Conferences & Expos that connect you with industry leaders, cutting-edge technologies, and innovations shaping the future of sustainable manufacturing.
Why EnabledFuture is the Right Partner for Technology Directors:
✅ Industry Expertise: Our team brings decades of experience in chemicals, catalysis, and battery supply chains. ✅ Tailored Solutions: We focus on both sustainability and profitability, thereby helping you drive innovation while optimising costs. ✅ Actionable Insights: With our in-depth market analysis and thought leadership, you’ll gain the strategic foresight to stay competitive in rapidly evolving markets.
Ready to Achieve Your Sustainable Technology Portfolios?
Staying competitive in the critical metals, catalysis, renewables and battery industries requires constant innovation and a deep understanding of emerging technologies. With our expertise, we help you turn sustainability into a business advantage.
Let’s collaborate to optimise your company’s offerings and ensure you achieve sustainable technology portfolios that meet the needs of the future.
Contact us for a free call to discuss how we can help you achieve your profitable and sustainable technology goals!
This intensive 1-day workshop will take place on Wed 6 Nov 2024 , 9:30-16:30 GMT at the IOM3, The Boilerhouse, Grantham location. The key topics include battery basics, sector specific applications, chronology of battery technology, technical deep dives, regulatory frameworks, resource management and techno-economics.
This course is relevant to anyone with an interest in overseeing operational efficiency, looking for eco-friendly solutions and identifying opportunities in green technology.
The course fee for this one-day programme based at The Boilerhouse in Grantham is £595 plus VAT at 20% where applicable. IOM3 members and subscribers to IOM3’s Business Partner Programme are entitled to a discount of 10% on the course fee. Fees includes CPD Certificate, lunch and refreshments